In short:
Big market moves. 5% 10Y. $106 oil. Busy primary markets – issuers taking advantage of strong demand, and avoiding the risk of market disruption later in the year.
Top talking points:
- Potential for disruption in the run up to the 3rd November US midterm elections: We may see higher oil prices in the coming weeks as the US-Iran conflict intensifies in the run up to the 3rd November US midterm elections. A fast oil price increase risks creating inflation, and disrupting markets.
- Fed rate hike strongly expected this Wednesday: Markets now imply a 92% probability of a 25bps rate increase at this week’s meeting (rate announcement is this Wednesday). This is on the back of inflation worries – following higher oil prices, inflation data continuing to be above the Fed’s target, and strong employment data.
- Long rates higher again – 10 year Treasury trades above 5% level: 10-year Treasuries traded above 5% today. High capital demand from AI capex and government spending are pushing up real rates. Inflation worries increase this further. 10-year real yields are now around 2.6%. We last saw material periods of real yields around this level in the early 2000s. It is worth noting though that this does not need to be a top – we frequently had real yields around 3.5% in the 1990s, and over 5% in the 1980s. These might be useful reference periods – with the development of computers fuelling investment and high government deficits.
- Potentially more primary issuance after the Fed announcement on Wednesday: A Fed hike on Wednesday (as expected) could give the market comfort that the Fed is actively managing inflation – and could result in a reduction in long-term rates volatility and potentially levels. We may see issuers who are waiting for more market stability issue soon after this.
- Growing issuance in EUR and GBP by US/international issuers: US issuers becoming large enough to move EUR and GBP credit markets. Uber raised €4.5 billion last week. Amazon issued its first GBP deal – borrowing GBP 4.25 billion. Non-European issuers FedEx, Teva Pharmaceuticals, Capital One and Pilgrim’s Pride (poultry processor) also issued in euros last week. Meta ran a non-deal roadshow in Europe – suggesting we are likely to get a large euro deal from Meta soon. For US issuers, these reverse Yankee deals can in some cases provide a cost advantage (after swapping back to USD) – but the bigger driver seems to be adding capacity beyond that available in USD.
Primary markets:
Markets reopened after the summer break.
Public Investment Grade – Issuance driven by pharmaceutical companies, financials, and tech. Deals included $6.5 billion from UK pharma group GSK (towards refinancing its $11 billion bridge loan for its acquisition of precision cancer therapy development company Nuvalent completed in July), $6 billion from UBS, GBP 4.25 billion from Amazon, $5 billion from Dell, $5 billion from Teva Pharmaceuticals (across EUR and USD), EUR 4.5 billion from Uber, $3.5 billion from MUFG, $3.4 billion from FedEx, $3 billion from Volkswagen, EUR 1.5 billion from Capital One.
Public High Yield – Aluminum company Alcoa raised $2.6 billion – for its acquisition of assets from South32. Lottery operator Brightstar Lottery sold EUR 500 million.
Private credit – ICG closed its ninth European corporate private credit fund at EUR 12 billion – adding around 90 new LPs to the strategy’s investor base. Claret raised EUR 575 million for its venture debt fund – the fund is so far invested in 27 companies including clinical-stage pharmaceutical, biotech, medtech, software. Bridgepoint announced a EUR 1.2 billion private credit continuation vehicle – led by private credit secondary specialist Pantheon. PennantPark closed a $745 million continuation vehicle – also led by Pantheon. Ares, Three Hills Capital Partners and Barings provided a GBP 700 million private credit facility to a consortium led by London-based investment manager Toscafund to buy UK hospital operator Spire Healthcare (the buyer consortium also includes Ares and Three Hills Capital Partners). Vantage Data Centers closed a $2 billion facility to support early-stage development across North America – placed with insurance and other institutional investors.
Sovereign/SSA – The UK sold GBP 4.25 billion of 30-year gilts – building an order book of GBP 85 billion – a demonstration of the high level of long-dated demand in sterling markets.
Syndicated loans – Radiopharmaceuticals company Curium (backed by London-based mid-market PE firm CapVest) secured $5.4 billion for its acquisition of Lantheus. Indonesian AI company Zankore (supported by NVIDIA through a revenue sharing agreement and credit-support arrangement) signed a term loan with five banks for $3.1 billion to buy NVIDIA GPUs. A number of other large deals are currently in marketing.
Asset-backed – Vantage launched a $540 million ABS deal backed by 13 data centers. GI Partners priced a $375 million data center CMBS.
EM – Middle East banks issued USD bond deals – including a $500 million deal from First Abu Dhabi Bank and a $500 million deal from Mashreq Bank. Turk Eximbank issued a $500 million bond. Indian mining company Vedanta Resources raised $400 million through a tap of its June issue.
Distressed/stressed:
Fitch said US private credit defaults over the last 12 months hit a record rate of 6.3%. Latvian airline airBaltic filed for Chapter 11 bankruptcy protection – as jet fuel prices increased this year. The airline says it has secured EUR 350 million from investors including Strategic Value Partners, Oaktree, Hayfin, Barclays and Morgan Stanley at an interest rate of around 12%.
What to watch this week:
- Fed rate increase on Wednesday – the market strongly expects a 25bps increase (from the current ‘3.5% to 3.75%’ range to a ‘3.75% to 4.0%’ range). If this happens we may see reduced volatility in long term rates as bond vigilantes get more comfort that the Fed will control inflation.
- Primary pipeline – may increase after Wednesday’s meeting. This could result in higher short-term new issue concessions if there is material bunching of new issues.
- Oil prices – Brent Crude now at $106. A further increase to around $120 as we saw in April could lead to a temporary credit market disruption.
Key data points:
Oil Price (Brent Crude): $106 (after going above $109 earlier today). Still the key macro figure to watch currently for debt markets.
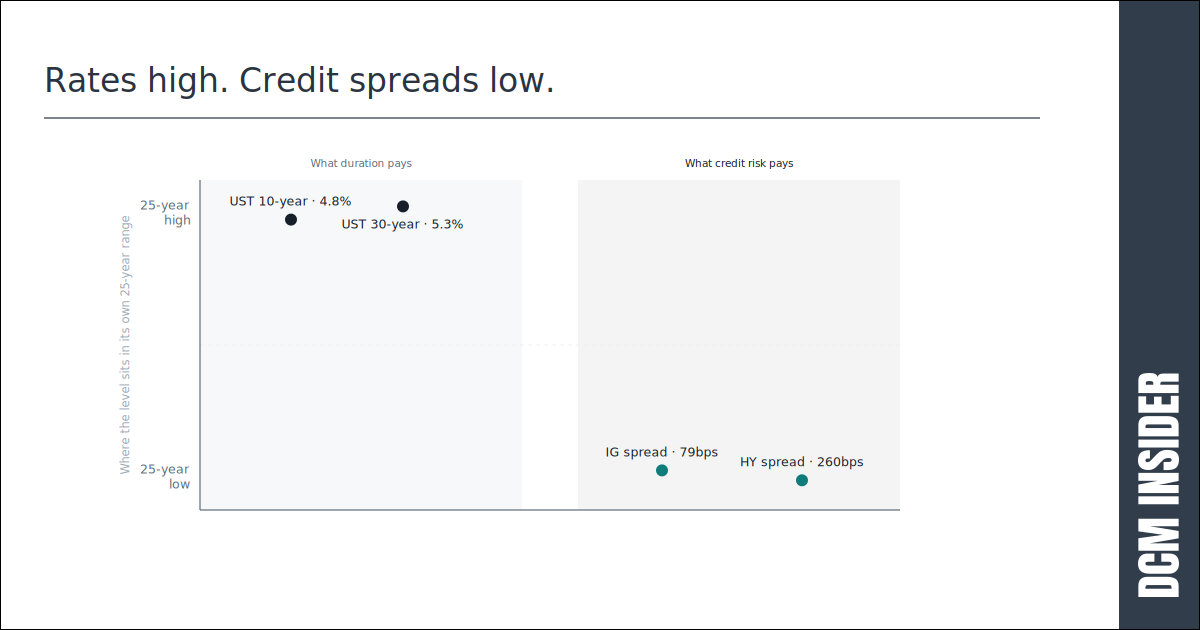
UST 10-year: 5.0%. Around 25-year highs.
UST 30-year: 5.4%. Around 25-year highs.
IG Spread (ICE BofA US Corporate OAS): 80bps. Down 1bp on the week. Around 25-year lows.
HY Spread (ICE BofA US HY OAS): 265bps. Flat on the week. Around 25-year lows.