The facts
Brent crude traded in the $60s for most of 2025. It started this month around $115. It fell to $90 earlier this week, and is currently $96.
The strategic incentives and constraints for each side in the Iran conflict may have changed following mid-term elections last week. This might increase the likelihood that we get to a quick resolution.
We are likely to see significant volatility in oil prices over the coming weeks as parties act to improve their negotiating position – for example military and economic actions by the US and Strait of Hormuz limitations by Iran.
But the chance of a resolution being found within the next few weeks/months seems to have increased.
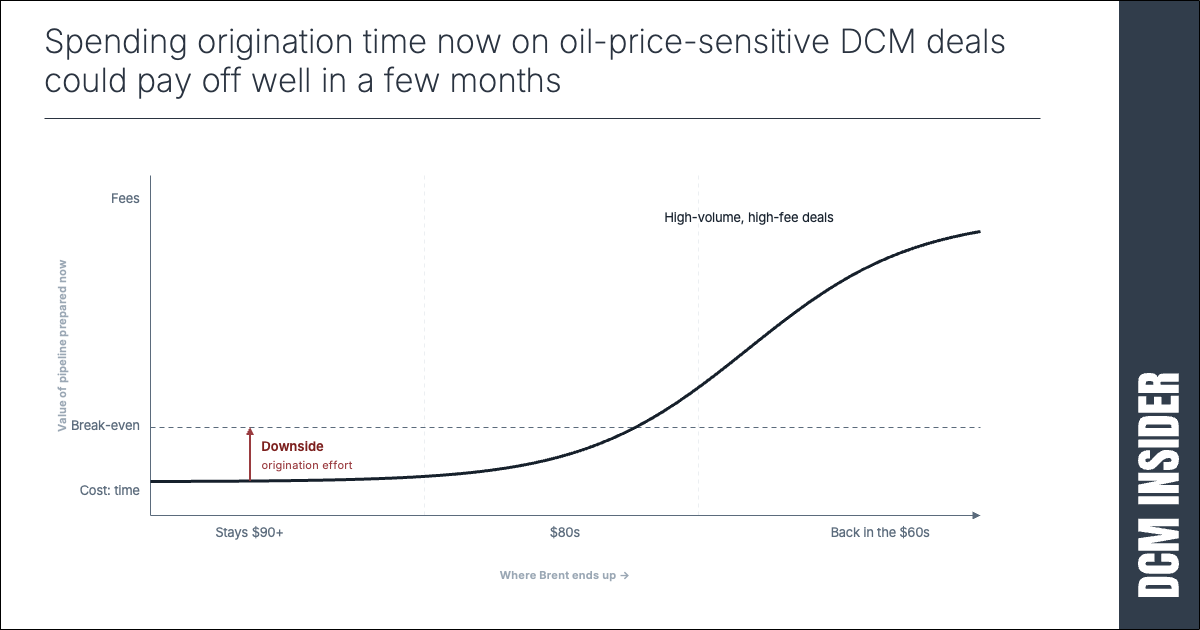
For DCM deal originators – investment bankers, private credit investors and lawyers – this may support putting time into originating deals that would become high volume/high fee if we get back to oil in the $60s.
In the subscriber part of this article, we run through how this affects issuers by sector, how it affects the debt capital markets, and how originators across investment grade bonds, high yield bonds, syndicated loans, structured credit, private credit, and stressed/distressed debt can act on this now.