In short:
Debt markets showing some stress. Widening in high yield – and especially at the CCC level. Primary starting to have a harder time – but still open. Issuers may want to consider locking in now to avoid risk (even if it means paying up a little).
Top talking points:
- $52 billion debt financing deal by Paramount Skydance: composed of $42.4 billion bonds and $9.5 billion loans – both across USD and EUR.
- Credit spreads widening – especially for low-rated bonds – showing a market that is starting to worry: spreads have widened beyond 300bps for high yield bonds and beyond 1,200bps for CCC and lower (up from 1,050bps a month ago). This is as investors worry about higher interest rates making it more difficult for stressed companies to refinance. Higher rates may make it particularly difficult to “kick the can down the road” – resulting in earlier defaults.
- Rates continue to increase: 10-year Treasury yields and 30-year Treasury yields are at their highest levels since 2002. There seems to be market momentum now towards higher yields – with this happening despite lower inflation and weaker jobs data than expected last week. This is largely driven by inflation expectations (including from high oil prices persisting/increasing), high capex demand for AI build-out, and high global government borrowing.
- Private credit continues to secure capital – including for asset-backed strategies: Oaktree raised $2 billion for its first asset-backed finance fund, and US mid-market focused Audax closed its direct lending fund at $10 billion in investable capital. Locked-in private capital may become particularly valuable if rates and yields continue to increase.
Primary markets:
The big deal was the $52 billion debt financing by Paramount Skydance to buy Warner Bros Discovery. Split across IG bonds, HY bonds, and loans – in USD and EUR. The bonds were oversubscribed ($109 billion peak order book for the IG bonds) and the deal got done – but there was some underperformance in the secondary market for the HY bonds.
Public Investment Grade – $30 billion of IG bonds from Paramount Skydance (6.3% for the 2-year bonds, 8.9% for the 40-year bonds). €1.9 billion from Deutsche Telekom. €1.5 billion from German grid operator Amprion. $1.5 billion from US supermarket chain Kroger.
Public High Yield – $12.4 billion second-lien bonds from Paramount Skydance (in USD and EUR tranches) – marking the largest HY bond of all time. £1.4 billion from UK gym operator PureGym (in GBP and EUR). $950 million from Norwegian Cruise Line.
Private credit – Strong institutional inflows. Oaktree raised $2 billion for its first asset-backed finance fund, and US mid-market focused Audax closed its direct lending fund at $10 billion in investable capital ($5.4 billion equity commitments). On the retail side, many non-traded BDCs continue to receive redemption requests well above their 5% gates.
Syndicated loans – $8.5 billion term loan B from Paramount Skydance (SOFR + 275bps at 99.75) and a €850 million term loan B (EURIBOR + 275bps at par). Tesla secured $30 billion in undrawn facilities from Citi and Wells Fargo. Electronics manufacturer Flex secured a $3.3 billion term loan towards its $4.4 billion acquisition of power converter manufacturer EPC Power. Commodities trader Trafigura secured $4.4 billion from 40 banks.
Asset-backed – Blackstone-owned QTS priced a $1 billion data center ABS. UK bank Lloyds priced a £1.5 billion UK auto ABS. European CLO issuance continued to be strong – with deals from Kartesia (its debut CLO), CVC, and Partners Group.
EM – $1.8 billion bond deal from Mexican airport operator ASUR (its international debut). Senegal debt restructuring – bilateral lenders are due to form a committee this week following initial discussions with the government.
Distressed/stressed:
CCC spreads widened significantly – suggesting we may see a fast-growing set of distressed/stressed companies. Car rental company Hertz hired PJT Partners to look at an amend-and-extend deal (its 2029 bonds are quoted around 30 cents).
Quotes of the week:
“With the policy action we took at our September meeting, there is no need for urgency.”
John Williams, New York Federal Reserve President
The market is currently pricing a rate increase for the 28th October Fed meeting at around 25%.
“The fact we have been 5.5 years above inflation target is playing with fire”.
Austan Goolsbee, Chicago Federal Reserve President
What to watch this week:
- High yield secondary trading – especially CCC level – If spreads continue to widen, this could cause a negative cycle – where widening spreads make it harder to issue, and so reduce credit quality – in turn widening spreads.
- Fed minutes – released on Wednesday. Will affect short and longer term rates as the market tries to understand how the Fed with Kevin Warsh as chair will act.
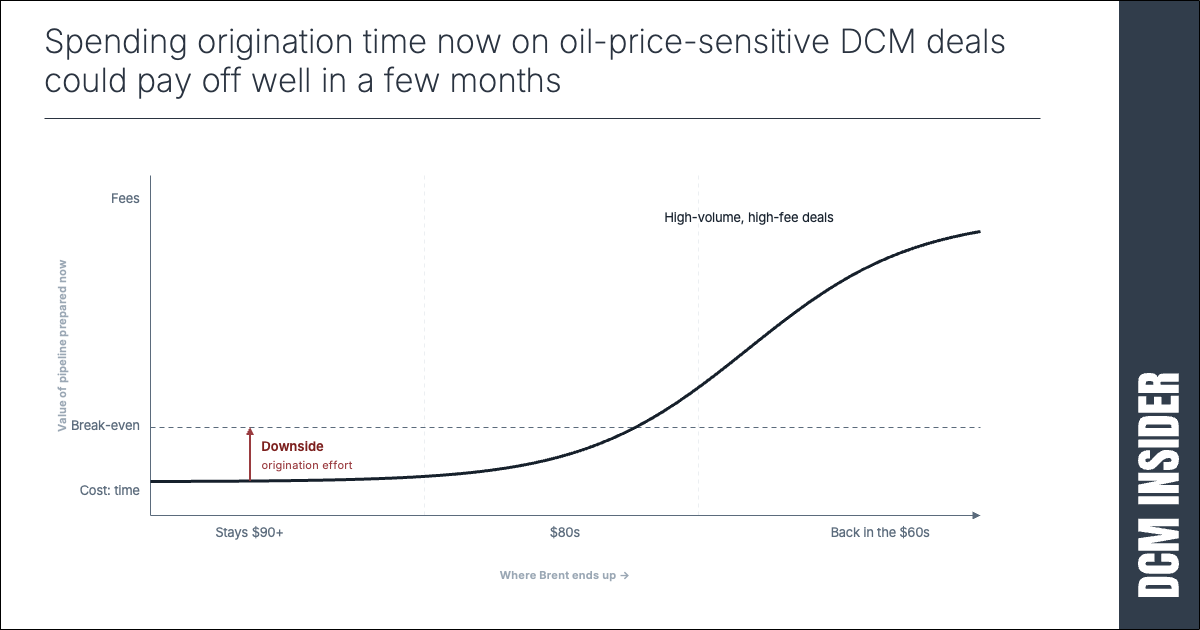
- Oil prices – there continues to be upside risk here. This is still likely the biggest driver for capital markets – though there may already now be contagion in terms of inflation expectations, rates markets upward momentum, and widening spreads. If oil prices turned materially lower – that might help to quickly reverse some of this.
Key data points:
Oil Price (Brent Crude): $100 (up $1 on the week).
UST 10-year: 5.3% (up 0.1% on the week). Highest since 2002.
UST 30-year: 5.7% (0.1% higher). Highest since 2002.
IG Spread (ICE BofA US Corporate OAS): 85bps. Up 4bps on the week.
HY Spread (ICE BofA US HY OAS): 310bps. Up 17bps.
CCC/lower Spread (ICE BofA CCC and lower OAS): 12%. Up 0.75% on the week.