In short:
Market sentiment worsening. Spreads widening. Markets closing to some low-rated credits (we are seeing pulled/postponed high yield and leveraged loan deals). High-grade issuers are active (particularly banks and M&A funding) – potentially locking in funds while markets are open. Possibility of an improvement after midterm elections on 3rd November. Issuers who are able to issue now may want to consider taking this opportunity to reduce their risk.
Top talking points:
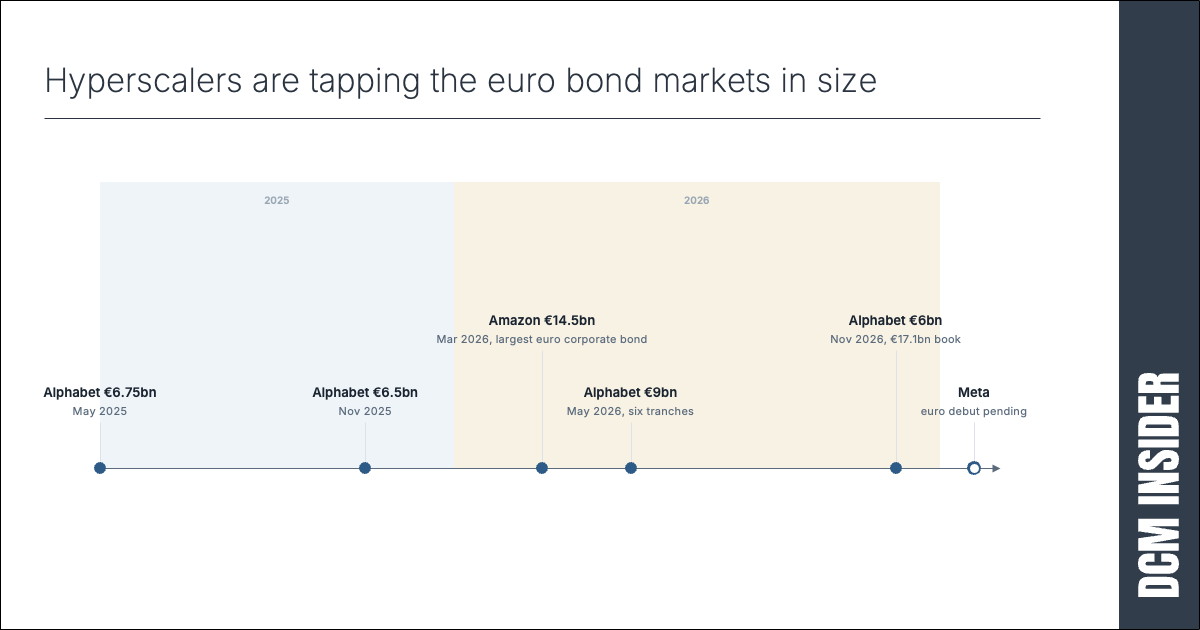
- Demand for AI credits falls (at a given price) on supply expectations: Meta reported $825 billion of future spending commitments (up from $700 billion in July). Meta CDS widened. Markets seem to keep getting surprised as AI issuers revise up capital needs.
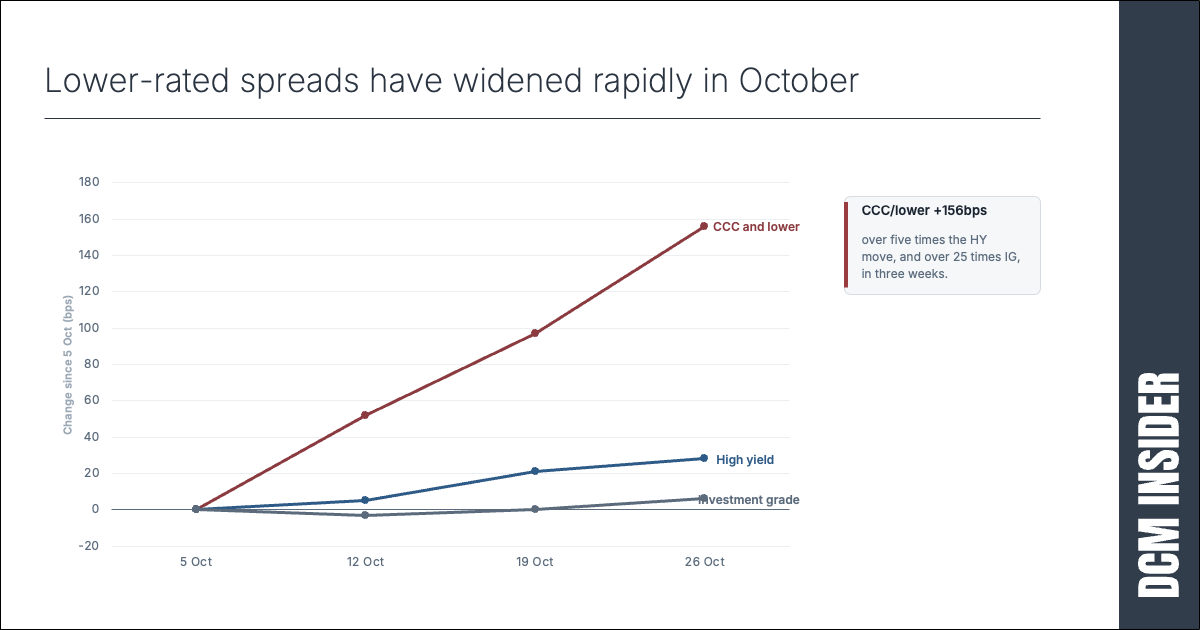
- Spreads widening across the board: IG spreads were up 6bps on the week to 91bps, HY up 7bps to 338bps and CCC/lower up 0.59% to 13.56%.
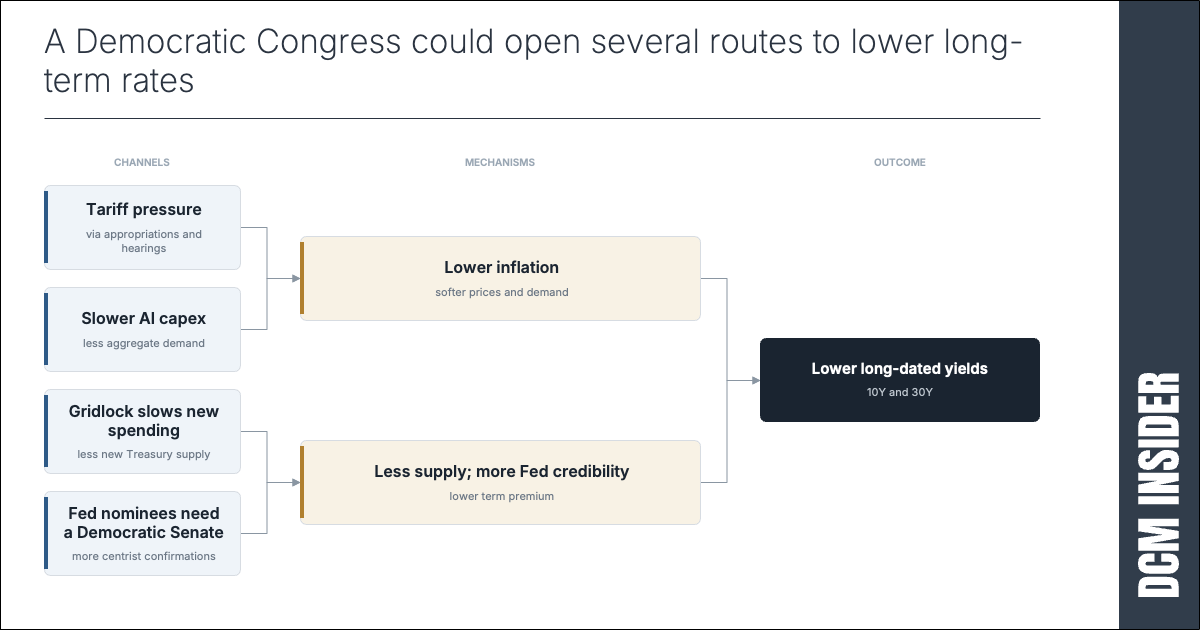
- Oil at $110+ and outlook uncertain with 3rd November midterm elections: Oil increased this week. There are concerns about escalation this week – ahead of midterms on 3rd November. And then what happens after midterms is uncertain as there are a number of political scenarios that could play out. If there is a rapid deescalation, that creates one scenario in which debt markets could become materially better (with lower inflation pressures and this supporting credit). There are other scenarios in which the situation could worsen and add to upwards rates pressure and credit quality stress.
Primary markets:
Public Investment Grade – $4.9 billion from consumer products company Kimberly-Clark to fund its acquisition of health products company Kenvue (the owner of Tylenol, Zyrtec, Neutrogena, Listerine, etc.), €2.75 billion from Citigroup, €2.75 billion from Wells Fargo, $3 billion from Walmart, $2.5 billion from software company Workday (showing SaaS companies can issue), $2.5 billion by Bank of America, $1.5 billion from PNC, $750 million from Citadel.
Public High Yield – Relatively light, with a number of deals being pulled/postponed. $550 million from LatAm oil and gas producer GeoPark.
Private credit – Arini Capital closed a $4 billion fund to lend to European mid-market companies. Partners Group closed a $510 million rated feeder for its evergreen credit strategy.
Syndicated loans – Negotiating power continues to shift to lenders. Lone Star’s €2.35 billion-equivalent buyout financing of ContiTech ended up making changes – including removing a clause that could have delayed defaults.
Asset-backed – Spreads widening but market still open. US data centre operator EdgeCore (facilities leased to Microsoft) widened pricing on its $521 million ABS and shortened its triple-B tranche. CLO refinancing and resets continued.
EM – Middle East issuance is restarting. Colombia-headquartered oil and gas company GeoPark issued a $550 million bond. Lula won Brazilian elections – which has been seen by the market as increasing credit risk.
Distressed/stressed:
Stock image company Getty Images filed a prepackaged Chapter 11 – implementing the restructuring it had agreed (including new equity).
What to watch this week:
- Mid-term election related events – This could include oil price changes.
- Fed decision – on Wednesday. The Fed is widely expected to keep rates unchanged this meeting (90% futures implied probability).
Key data points:
Oil Price (Brent Crude): $110 (up $1 on the week).
UST 10-year: 5.0% (down 0.1% on the week). Around highest levels since 2002.
UST 30-year: 5.3% (0.2% lower). Around highest levels since 2002.
IG Spread (ICE BofA US Corporate OAS): 91bps. Up 6bps on the week.
HY Spread (ICE BofA US HY OAS): 338bps. Up 7bps. Risen rapidly. Compare with 266bps on 21st September.
CCC/lower Spread (ICE BofA CCC and lower OAS): 13.56%. Up 0.59% on the week. This was less than 10% in July.