In short:
M&A and AI driving DCM primary. $50 billion+ from Paramount Skydance. $10 billion+ deals from Sysco and SoftBank. High-yield starting to widen – risk this could spread up the credit spectrum over the next few months.
Top talking points:
- M&A driving debt markets new issuance: Many $5 billion+ M&A financing deals. Paramount Skydance’s $52 billion debt for its $110 billion acquisition of Warner Bros Discovery is the largest – borrowing across the investment-grade bond, high-yield bond and syndicated-loan markets.
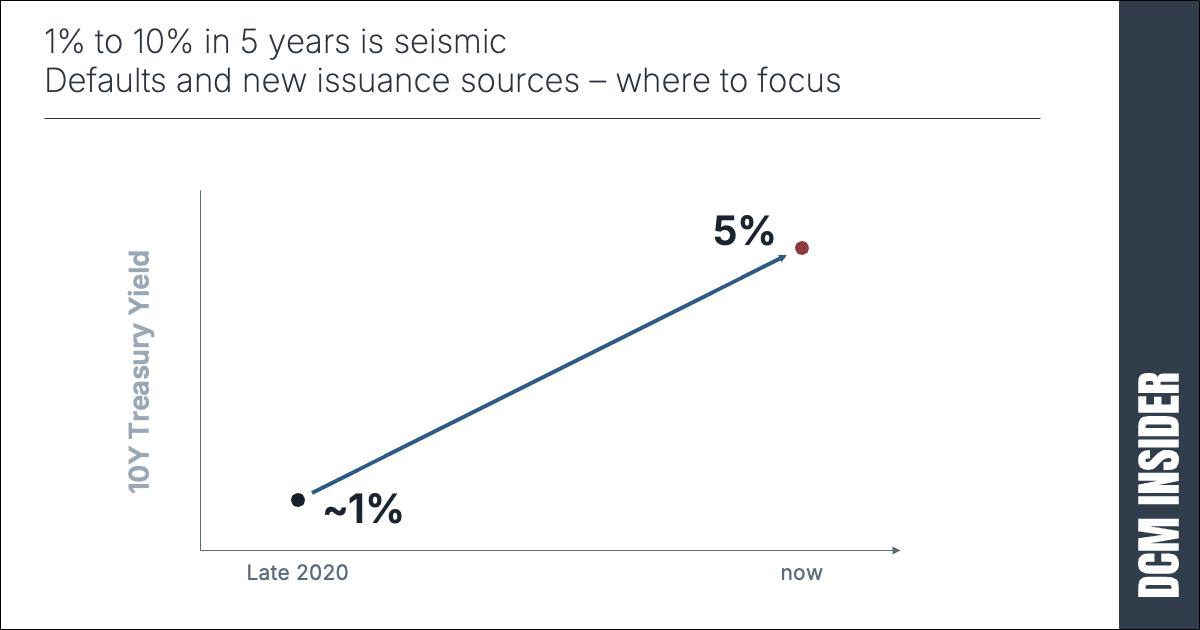
- Rates continued to increase: 10-year Treasury at 5.2%, 30-year at 5.6%. Markets now imply a 70% probability for another rate hike at the October 27th/28th Fed meeting. Fed may need to be much more forceful in increasing short-term rates to avoid the risk of rates continuing to drift upwards.
- Oil price as a core risk for stagflation – October could be particularly eventful: The Iran conflict may escalate ahead of 3rd November midterms. This could increase oil prices. Brent crude traded up to $108 last week. It is now back to $99.
- Oracle’s force majeure notice shows risks of AI data center project finance: Oracle is reported to have issued a force majeure notice to the developer of a data center which Oracle will lease – stating that it is having difficulty securing power in time. This could risk delaying the start date of full payments from Oracle on the data center (scheduled for 2028). There may be no delays or economic effects in this case, but the reports bring focus to development risk for data centers – which could lead to higher financing costs and tighter terms for data center development projects going forward.
- Spread dispersion – with high yield spreads widening: High-yield spreads are widening. Concerns around higher rates, AI disruption to revenues, and the risk of stagflation/recession starting to create worries about defaults.
Primary markets:
The big drivers – M&A financings, AI-related financings, bank issuance.
Public Investment Grade – Paramount Skydance launched a $44 billion bond deal today ($32 billion senior IG and $12.4 billion sub-IG – across USD and EUR) – pricing expected on Wednesday. $17 billion ($12 billion IG senior, $5 billion sub-IG hybrids) from food distributor Sysco – to fund its Jetro Restaurant Depot (a food wholesaler) acquisition – including $14.6 billion in USD, €1 billion in euros, and C$1.5 billion in Canadian dollars. $3.7 billion from TD Bank. $2.7 billion (in USD and GBP) from US asset manager Nuveen to fund its acquisition of Schroders.
Public High Yield – SoftBank (BB+) issued the largest HY bond deal of all time at $11.1 billion – comprising $10 billion in USD and EUR 1 billion in euros. The USD bonds priced at 8.625% for 3.5 years, 9.25% for 5.5 years, and 9.75% for 7.5 years. The $12.4 billion HY bonds from Paramount Skydance currently being marketed should take this record of the largest HY bond deal of all time from SoftBank. $1.25 billion (7% 2032) from data center power supplier Solaris Energy Infrastructure. EUR 2 billion hybrids from Bayer.
Private credit – Cheyne raised GBP 3 billion for its European real estate lending strategy. JPMorgan Asset Management and Qatar Investment Authority announced a $5 billion partnership to jointly provide senior loans to US mid-market companies (as part of a bigger $20 billion partnership – the other $15 billion is for public equities). Neuberger ($615 billion AUM) launched a new aircraft debt platform – and is looking to build a $2 billion+ portfolio.
Syndicated loans – Paramount Skydance launched a $7.5 billion term loan B (dollars and euros) – towards its acquisition of Warner Bros Discovery. Australian AI company Firmus is reported to be looking to borrow $7.5 billion to buy NVIDIA GPUs for an Indonesian data center (the deal would likely include credit support from NVIDIA – like the recent $3.1 billion loan by Indonesian AI venture Zankore).
Asset-backed – REIT BrightSpire priced a $960 million commercial real estate CLO. Blackstone reportedly pulled a $3 billion collateralised fund obligation (CFO) backed by a portfolio of 700 PE fund holdings on weak investor demand – with possible concerns about the underlying assets. Europe active with consumer and auto ABS. Fintech-funder Fasanara priced its first CLO.
EM – $1.6 billion bonds by the Dominican Republic. $1.5 billion bonds by Türkiye.
Distressed/stressed:
Brightline (debt around $5 billion) – the high speed railway between Orlando and Miami – filed for Chapter 11 bankruptcy protection. An out-of-court restructuring for US specialty material manufacturer Loparex is expected to reduce debt by $400 million – potentially wiping out its $160 million junior loan. The originally AAA tranche on the securitization of Philadelphia Centre Square office towers (property valued at $470 million in 2019) may suffer a 50%+ loss – as occupancy has fallen, and now a judge has approved a sale of the building for $70 million. All the below-AAA tranches could get no recovery. CCC spreads are widening – increasing dispersion between high grade and low grade credits.
Quotes of the week:
“The risks to inflation outweigh the risks to maximum employment.”
Tom Barkin, FOMC member
What to watch this week:
- Execution of Paramount Skydance’s $52 billion financing – A test of market capacity. Expected to find plenty of demand. Should provide confidence to issuers and bridge funders of other very large M&A.
- Oil prices – this remains the biggest swing factor. There is a risk for escalation through October ahead of US midterms on 3rd November.
- PCE and payrolls data: PCE (inflation) data is out on Wednesday. Nonfarm payrolls is out on Friday. A surprise to either could materially move markets.
Key data points:
Oil Price (Brent Crude): $99 (up $3 on the week). Still the key macro figure to watch for debt markets.
UST 10-year: 5.2% (up 0.2% on the week). Around 25-year highs.
UST 30-year: 5.6% (0.3% higher). Around 25-year highs.
IG Spread (ICE BofA US Corporate OAS): 81bps. Up 4bps on the week. Around 25-year lows.
HY Spread (ICE BofA US HY OAS): 293bps. Up 25bps.